
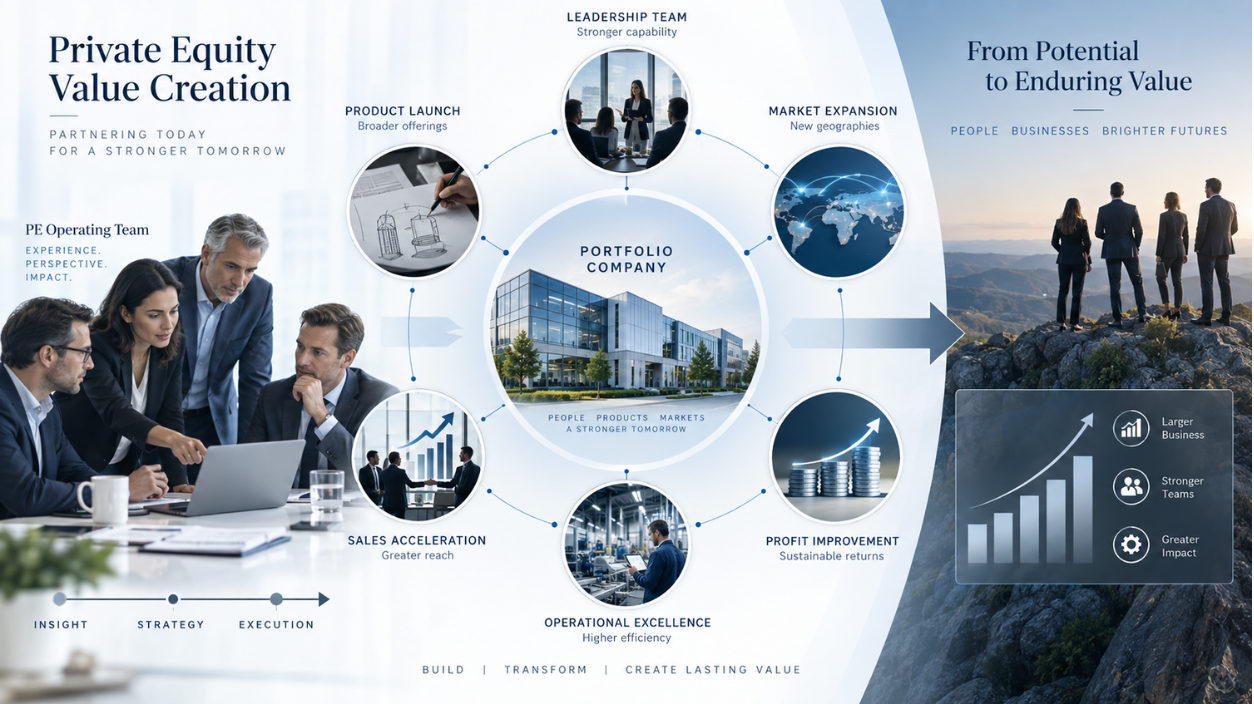
Private equity value creation used to have a simple engine. Buy right, add leverage, wait for multiples to expand, and sell. For deals done between 2010 and 2022, that engine accounted for 59% of returns, according to McKinsey’s analysis with StepStone Group. It worked because debt was cheap and multiples kept climbing. Neither is reliably true anymore.
What’s replaced it is less comfortable to admit out loud but shows up clearly in the numbers. Operating partners now drive roughly 47% of value creation in buyouts, up from just 18% in the 1980s. GPs who lead with operational focus post a 2 to 3 percentage point IRR premium over those who don’t. On a $1B fund, that’s $20-30M in LP value that came from how a business was run, not how it was financed.
Private equity value creation, in other words, has become an execution story. McKinsey’s own phrasing on this is unusually direct for an industry that likes nuance: impact counts, not the plan. Bain’s 2026 Global PE Report backs it up. Revenue growth drove 71% of 2024 exit value, up from 64% the year before. Most VCPs on paper already look reasonable. What separates the top quartile is no longer the plan. It’s who can actually deliver it, and how fast.
Why Traditional Private Equity Value Creation Models Are Being Challenged
There’s a reason so many funds are re-reading their VCPs this year. The math underneath them has shifted, quietly, over the last few vintages:
- Entry multiples compressed from 11.9x to 11.0x EBITDA through the first nine months of 2023.
- Debt got more expensive and harder to source on favorable terms.
- The growth bar moved. Bain’s framing sums it up well: “12 is the new 5.” Funds now need close to 12% annual EBITDA growth to hit returns that 5% growth once delivered.
- LP scrutiny shifted. McKinsey’s January 2026 LP survey shows IRR still matters, but disciplined underwriting and demonstrated operational capability are now priced in as separate, weighted factors.
None of this is a cyclical dip that reverses itself. A fund that can point to real operational muscle is being underwritten differently today than one leaning on structuring alone.
The Shift From Financial Engineering to Operational Transformation
The 2-3 point IRR gap between operationally focused GPs and everyone else isn’t new information inside the industry. What’s changed is how precisely it can now be measured, and how uncomfortable it’s become to ignore.
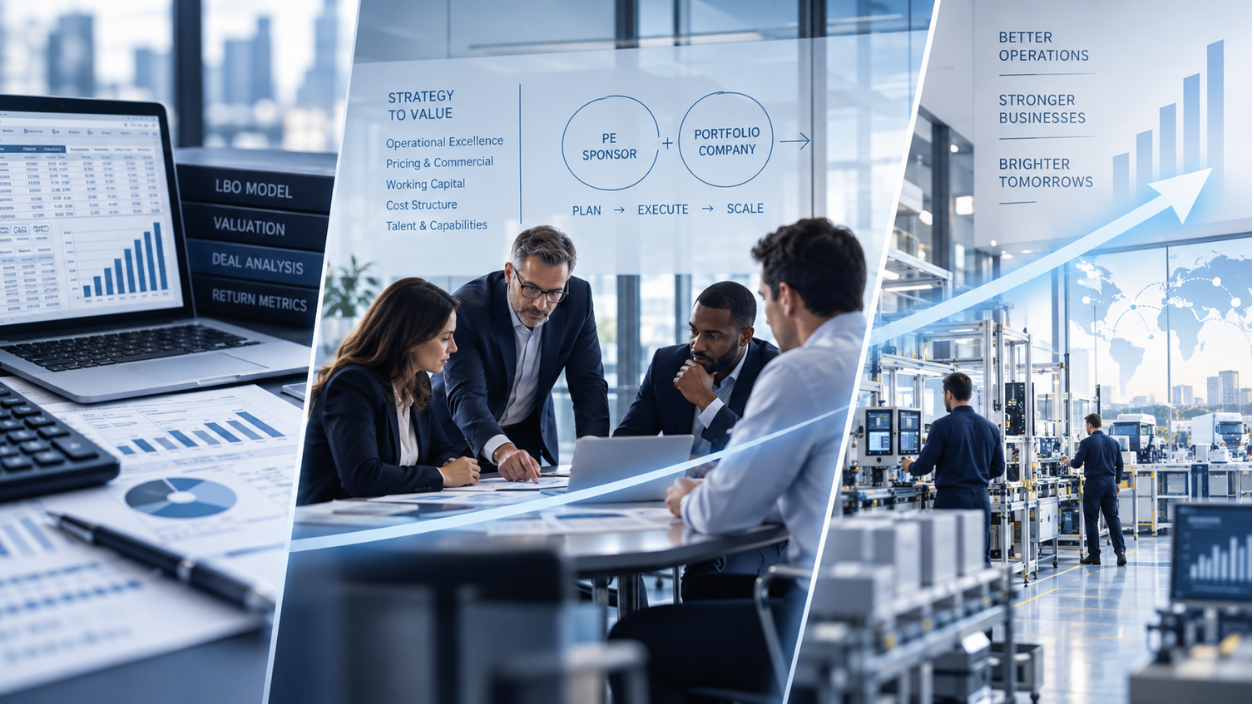
McKinsey’s broader work on value creation levers puts the available upside at 25-45% margin growth, achievable through operational work alone. Three levers do most of that work: working capital and cash discipline, pricing, and cost structure. Pricing carries the most leverage per unit of effort, and it’s also the most underused. A 1% pricing improvement lifts profit by 6% on average for a typical midsize company. A 1% cut in variable cost buys 3.8%. Fixed cost cuts buy 1.1%. Most management teams still spend more energy on the smaller number.
The Real Value Creation Gap: Strategy Exists, Execution Often Does Not
CVC has reviewed hundreds of Value Creation Plans across the industry, and its own framework for what separates the strong ones from the rest lands on a distinction worth sitting with: “revenue was down 10%” is a fact. “Sales training, collateral, and incentives are off market” is a root cause. Plans that stop at the fact tend to look complete and fail anyway.
The plans that hold up share a pattern. An independent, time-boxed diagnostic, typically 6-10 weeks, forces a genuine root-cause view before anyone commits to a fix. Skip that step, and a VCP tends to become what CVC bluntly calls a value creation dream rather than a value creation plan. The gap between the two isn’t intelligence. It’s discipline, applied early, before the story the deal team wants to believe gets baked into the plan.
The binding constraint on most VCPs isn’t the plan. It’s whether the person running the business day to day can execute it at PE speed. Founders and long-tenured operators built the business and know it cold, but a 100-Day plan, a Buy & Build integration, or an IPO-readiness push demands a different gear than steady-state operating. Waiting for attrition to surface that gap costs a fund months it doesn’t have. Closing it deliberately, as its own workstream inside the VCP, has become table stakes rather than a nice-to-have.
How Private Equity Firms Are Creating Value Through Operational Excellence
The funds pulling ahead operationally tend to run the same playbook, even when the sectors look nothing alike:
- A quantified hypothesis for every initiative, with a named owner accountable for its EBITDA or cash impact, not a shared responsibility that quietly belongs to no one.
- Weekly value reviews, not quarterly ones. Real-time portfolio monitoring has made this the new baseline.
- Working capital and cash discipline addressed first, since liquidity is what funds every other initiative on the list.
- The first 100 days spent proving early wins, not drafting new hypotheses that could have been tested in diligence.
Case Example — Improving Manufacturing and EBITDA Performance
An RV-sector HVAC manufacturer heading toward a 12-15 month exit needed EBITDA gains that would hold up under buyer scrutiny, not gains that would look good on a slide. A five-week diagnostic across five plant locations found specific, unglamorous production-line and layout changes. The result was 500 basis points of EBITDA improvement inside that same 12-15 month window, per TBM Consulting Group’s published case data. Nothing about the lever was exotic. It was narrow, well-scoped, and it showed up exactly where a buyer would look for it.
Technology and AI Adoption as a New Private Equity Value Creation Lever
CVC ran generative AI diagnostics across more than 120 portfolio companies and sorted each one by exposure, imminent disruption, medium-term transformation, or low risk, before deciding where to spend. Multiverse Group, an Italian online education platform, became the proof point for that approach: an “MVP accelerator” that scoped, built, and tested AI use cases against real student and faculty workflows instead of deploying tools on a hunch.
That kind of discipline matters because the industry-wide gap between AI investment and AI impact is still wide. Only 6% of GPs currently see AI delivering high impact on their own internal operations, but 70% expect high impact within three to five years, per McKinsey’s 2026 Global Private Markets Report. Inside diligence specifically, AI-assisted processes are already cutting costs by up to 70% and assessment time by roughly half, so the technology clearly works. The question is who’s actually capturing it yet.
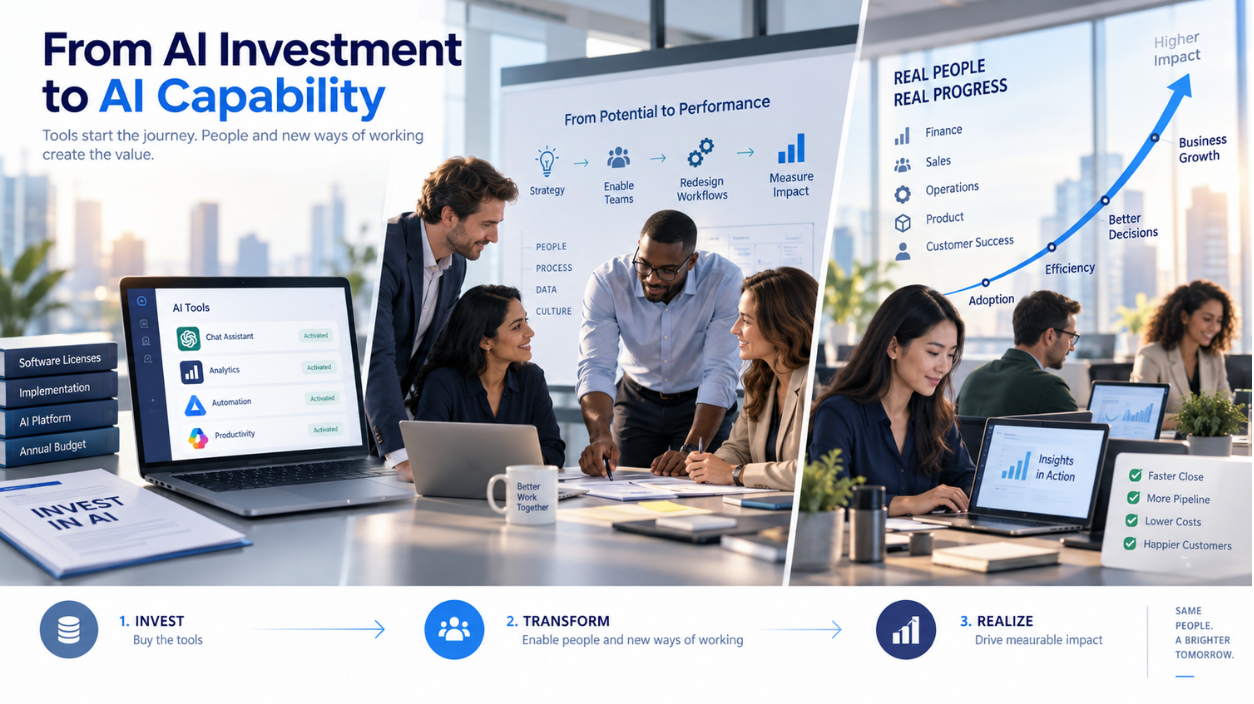
Licenses get bought in an afternoon; that 6%-to-70% gap has little to do with tooling. What takes longer, and what actually determines whether AI spend shows up in EBITDA, is whether a finance team, a sales team, or an ops team changes how it works day to day because of it. The funds showing up early in that “high impact” cohort are the ones treating AI adoption as a change-management workstream inside the VCP, with owners and milestones, rather than a line item in the tech budget.
If pricing is the most underused lever in the industry, LLR Partners’ work with portfolio company HRS is a useful reminder of what happens when a fund actually uses it. A GTM realignment and sales reorganization, tied directly to the VCP, moved gross margin from 61% to 68% within 18 months and grew bookings 94% year-over-year. Nothing about that result came from a bigger sales team. It came from a commercial engine that was rebuilt on purpose.
Creating Scalable Sales and Customer Capabilities
The margin number isn’t the interesting part of the HRS story. What matters more is that the gains came from repeatable playbooks, forecasting discipline, and pricing structure built to survive past one strong quarter. That’s the difference between a result and a capability. A result fades. A capability travels, across a Buy & Build platform, into the next add-on, without resetting from zero every time
Why Capability Building Is Becoming Central to Private Equity Value Creation
The shift from 18% to 47%, in where value creation actually comes from, is a capability story whether the industry frames it that way or not. Every VCP milestone, a new CFO, a pricing sprint, a Buy & Build integration, creates a specific capability demand at a specific moment. The funds capturing that 2-3 point IRR premium consistently aren’t the ones with the best plans. They’re the ones that can meet that capability demand on the VCP’s timeline instead of the organization’s natural hiring cycle.
From Knowledge Transfer to Business Transformation
Generic training transfers knowledge and moves on. It rarely moves margin. What actually shows up in the numbers a buyer underwrites at exit is capability work tied to a named KPI, gross margin, pipeline coverage, cash conversion, inside the same weekly review rhythm the rest of the VCP runs on. Anything less specific tends to get reported as activity rather than results.
How HUKSA Supports Private Equity Value Creation
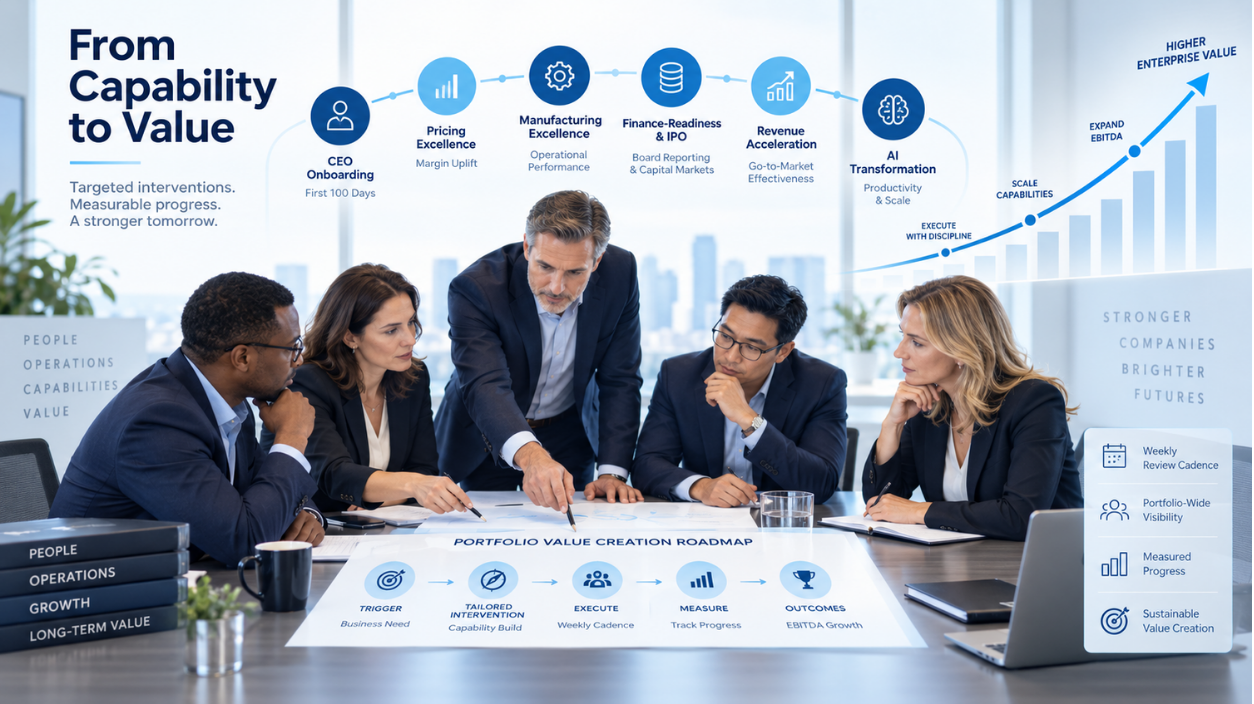
Huksa operates as the embedded execution layer behind the Value Creation Plan. Operating Partners set the direction; Huksa deploys expert-led interventions mapped to each VCP stage:
- Entry — an independent capability diagnostic feeding the root-cause view.
- 100-Day — executive onboarding and early commercial wins.
- Transformation — operational excellence and AI adoption.
- Scale — leadership bench-building and Buy & Build readiness.
- Exit — IPO-readiness and governance capability.
Where firms like KKR and Warburg built internal Capstone-style operating teams over years, Huksa runs on a standing network of 145,000+ practitioners across 55+ sectors, which means programs can stand up in weeks rather than quarters. A dual-view dashboard gives each portfolio company its own progress view while the fund tracks capability deployment and adoption across every portco from a single place, the same weekly-cadence visibility the rest of the operating model already runs on.
Business-Aligned Capability Journeys
Every intervention maps to a named business trigger inside the VCP, not a generic curriculum handed down from HR. A new CEO gets an executive onboarding journey built for the first 100 days. A pricing squeeze gets a pricing excellence sprint. An IPO push gets board-reporting and finance-readiness capability. Signature programs, including the Revenue Acceleration Playbook, Manufacturing Excellence Playbook, and AI Transformation Playbook, are built around exactly these triggers, with the same weekly review cadence built in from day one.
The Future of Private Equity Value Creation
The trajectory is already visible in the data, not a prediction resting on theory. Operating partners went from 18% of value creation in the 1980s to 47% today, and that line hasn’t leveled off yet. As EBITDA growth targets sit near 12% and hold periods stretch toward six years, the funds with embedded execution capability will keep separating from the funds still waiting for a favorable exit multiple to bail them out.
Conclusion
Private equity value creation has moved past the point where a strong plan alone wins, and the industry’s own numbers make the case better than any single argument could:
- Operating partners now drive 47% of buyout value creation, up from 18% in the 1980s.
- Operationally focused GPs earn a 2-3 point IRR premium, worth $20-30M on a $1B fund.
- Revenue growth, not leverage, drove 71% of 2024 exit value.
- The gap that remains is a capability gap — closing it, on the VCP’s own timeline rather than the organization’s natural pace, is what separates funds that talk about operational value creation from funds that actually capture it.
The plan gets a deal underwritten. Capability is what gets it to exit.
FAQs
- What does private equity value creation entail?
Every lever used to grow a portfolio company’s worth across the hold period, operational transformation, revenue growth, commercial execution, technology adoption, and leadership capability, working alongside disciplined financial structuring rather than in place of it. - What is it about operational transformation that makes it important in the field of private equity?
It’s become the primary return driver. Leverage and multiple expansion accounted for 59% of returns in 2010-2022 deals; that mix has reversed as operating partners now drive 47% of value creation, up from 18% in the 1980s. - What do private equity firms do to generate value after they have acquired a company?
They run a phased VCP, a root-cause diagnostic at entry, early wins in the first 100 days, operational and commercial transformation through mid-hold, and readiness work ahead of exit, each with a named owner and a weekly review rhythm rather than a quarterly one. - Why is operational transformation important in private equity?
Because it’s the source of the 2-3 point IRR premium McKinsey documents for operationally focused GPs, at a moment when compressed entry multiples leave less room for returns built on multiple expansion alone. - How do PE firms create value after acquiring a company?
Through working capital and pricing discipline, commercial excellence, AI-enabled operations, and leadership capability, sequenced against VCP milestones from Entry through Exit rather than addressed all at once. - What role does capability building play in private equity value creation?
It’s the execution mechanism underneath the plan. The VCP sets the target; capability determines whether the portfolio company’s team can actually hit it on the timeline the fund needs, not eventually. - How can portfolio companies accelerate growth after PE investment?
By closing leadership and commercial capability gaps inside the first 100 days, and holding every initiative to a quantified hypothesis, a named owner, and a weekly review rhythm from the start.